Market Maker Economics: Why Liquidity Leaves When You Need It
The most reliable observation in market structure is that liquidity is abundant when you do not need it and absent when you do. That is not a failure of the participants providing it — it is the direct consequence of how they get paid and how they lose.
By Olivia Bennett, Blockchain Security Researcher
Smart Contract Security, Audit Reports, Exploits, DeFi Hacks, White-Hat Research
✓ Reviewed by Emily Volker· Editor-in-Chief
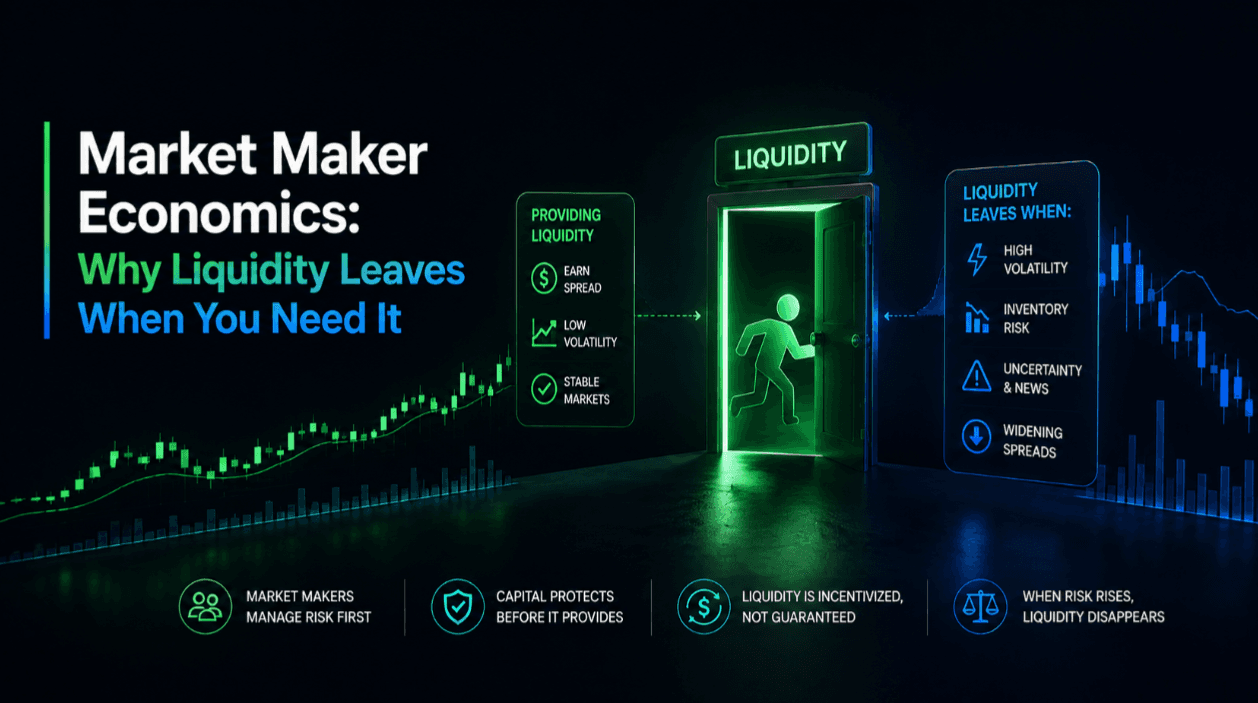
A market maker quotes a price to buy and a price to sell, earning the difference when both sides trade. The business is a race between spread income from traders with no particular view and losses to traders who know something. Every feature of market behaviour that frustrates other participants descends from that arithmetic.
The two counterparties
Uninformed flow — someone rebalancing, converting, or acting on no particular edge — is profitable to trade against. The maker buys at the bid, sells at the offer, and the spread is earned.
Informed flow is the opposite. Someone trading because they know the price is about to move takes the maker's quote precisely when it is wrong, and the maker is left holding a position that immediately loses.
The maker cannot distinguish them in advance. The spread is therefore priced so that the earnings from the first group exceed the losses to the second, in aggregate, over time. That single equation explains almost everything about how quoted markets behave.
Why spreads widen when it matters
In volatile conditions, the proportion of informed flow rises. People trade because something happened, and the maker's quote is more likely to be stale relative to information the other side already has.
The rational response is to widen the spread — charging more to compensate for being picked off more often — and to reduce quoted size, limiting how much can be taken at a wrong price.
Both happen automatically and simultaneously across every maker in a market, which is why depth evaporates rather than degrading gently. It is not coordination and it is not abandonment. It is the same calculation producing the same answer at the same moment.
The uncomfortable implication is that a market's liquidity is at its thinnest exactly when a liquidation engine most needs it to be thick, which is the structural reason cascades are possible at all.
Inventory, and the cost of holding it
A maker who buys must eventually sell, and while holding the position they are exposed to the market. Managing that inventory is most of the operational work.
In traditional markets, hedging is cheap and available around the clock. In crypto it is uneven: hedging instruments exist for major assets and thinly or not at all for the rest, which is why spreads on long-tail assets are wide regardless of trading interest. The maker cannot lay off the risk, so they charge for carrying it.
This also explains why liquidity does not follow attention. An asset with heavy retail interest and no hedging market will have poor depth, because the constraint is on the maker's ability to manage inventory rather than on demand for the asset.
Automated market makers face the same problem differently
A pool cannot widen its spread or pull its quotes. It provides the same curve regardless of conditions, which means it is picked off by informed traders continuously and has no defence.
That loss is the well-known cost of providing liquidity to a pool, and it is not an inefficiency to be engineered away — it is the same adverse selection that a human maker manages by quoting wider, borne instead as a persistent transfer.
Which is why fee income has to exceed it for pool provision to be worthwhile, and why concentrated liquidity, which allows repositioning, is best understood as giving pool capital some of the defensive ability a quoting maker has always had.
What this means in practice
- Expect depth to disappear during volatility and size positions on the assumption that it will.
- Treat displayed depth as an upper bound at all times and a poor one during stress.
- Understand that wide spreads on long-tail assets reflect hedging difficulty rather than lack of interest.
- For liquidation risk specifically, model exit liquidity at stressed levels rather than average ones.
- Recognise that both quoted and pooled liquidity face the same adverse selection, and only one of them can react.
None of this is a criticism of market makers. It is a description of a business that only functions because it is allowed to withdraw, and the withdrawal is the feature that keeps anyone willing to quote at all.
Sources
2 references- 01Concentrated liquidity
Uniswap · accessed August 22, 2026
- 02The Uniswap Protocol
Uniswap · accessed August 22, 2026
Frequently asked questions
Why does liquidity vanish during volatility?+
Because the share of informed flow rises, and a maker quoting into it gets picked off more often. The rational response — wider spreads and smaller size — happens simultaneously across every maker, so depth evaporates rather than degrading gently. It is the same calculation producing the same answer at once.
Why are spreads on small tokens so wide?+
Usually because the maker cannot hedge. Managing inventory requires somewhere to lay off risk, and for long-tail assets that market frequently does not exist. The spread compensates for carrying the position, which is why liquidity does not follow attention.
Do AMMs solve this?+
No, they face the same adverse selection without the ability to react. A pool cannot widen its curve or withdraw when informed flow arrives, so it is picked off continuously and bears the cost as a persistent transfer. Fee income has to exceed it for provision to be worthwhile.
Why does this matter for liquidations?+
Because a liquidation engine needs depth at exactly the moment makers are withdrawing it. Exit liquidity modelled on average conditions overstates what is available when it is needed, which is the structural reason cascades happen at all.
Written by
Olivia BennettBlockchain Security ResearcherSmart Contract Security, Audit Reports, Exploits, DeFi Hacks, White-Hat Research
Olivia Bennett is the Blockchain Security Researcher at CoinRadar Daily, where she specializes in smart contract security, DeFi risk analysis, blockchain infrastructure, and protocol vulnerabilities. Drawing on years of hands-on cybersecurity experience, she delivers in-depth reporting that explains both the technical details and the real-world implications of security incidents across the digital asset ecosystem. Before joining CoinRadar Daily, Olivia built her career in cybersecurity, working in penetration testing, blockchain security assessments, and smart contract auditing. She participated in numerous security reviews for decentralized applications and blockchain protocols, helping identify critical vulnerabilities before they could be exploited. Her responsible disclosure work has contributed to improving the security of several major DeFi projects and protecting millions of dollars in digital assets. Olivia earned a Bachelor of Science in Computer Science from the University of Edinburgh and later completed advanced professional training in offensive security and blockchain technologies. Her combination of software security expertise and blockchain knowledge enables her to provide readers with clear, evidence-based analysis of exploits, protocol upgrades, and emerging attack vectors. At CoinRadar Daily, Olivia publishes detailed investigations into blockchain exploits, smart contract audits, cross-chain security, wallet protection, and evolving cyber threats affecting the crypto industry. She is particularly committed to translating highly technical research into practical guidance that helps investors, developers, and blockchain users better understand protocol risk and security best practices. Alongside her editorial work, Olivia contributes educational resources covering secure wallet management, decentralized finance security, and blockchain infrastructure. She also participates in industry events and technical discussions focused on strengthening Web3 security standards, supporting CoinRadar Daily's mission to provide accurate, research-driven coverage of the rapidly evolving digital asset landscape.
✓Reviewed & edited by
Emily VolkerEditor-in-ChiefEditorial Strategy, Investigative Journalism, Crypto Media, E-E-A-T Standards
Emily Volker is the Editor-in-Chief of CoinRadar Daily, where she leads a multilingual editorial team covering cryptocurrency markets, blockchain innovation, Web3, and global digital asset regulation across eight languages. With more than a decade of experience in financial and technology journalism, she has played a key role in developing high editorial standards and trusted reporting within the digital asset industry. Emily began her career as a financial journalist reporting on commodities, energy markets, and emerging technologies before discovering Bitcoin and decentralized finance in the early 2010s. She later moved to London to join one of Europe's early blockchain-focused media organizations, where she advanced into senior editorial leadership. Her experience reporting through both the rapid expansion of the 2017 ICO boom and the subsequent market correction reinforced her commitment to fact-based, research-driven journalism in an industry often influenced by speculation. She holds a Master's degree in International Journalism from City, University of London, and has completed executive studies in digital media strategy through the Reuters Institute at Oxford. Emily is a strong advocate for editorial transparency, rigorous verification, and responsible financial reporting. She also helped integrate Google's E-E-A-T principles—Experience, Expertise, Authoritativeness, and Trustworthiness—into the editorial standards followed by CoinRadar Daily. Under her leadership, CoinRadar Daily has expanded into a global cryptocurrency news platform publishing content in eight languages with a network of editors, analysts, and contributors across four continents. Emily oversees investigative reporting, editorial policy, content quality, and fact-checking processes to ensure every article meets the publication's standards for accuracy, credibility, and independence. Alongside her editorial responsibilities, Emily mentors aspiring journalists through digital media initiatives and regularly speaks at international conferences focused on journalism, fintech, blockchain technology, and digital assets, where she discusses responsible reporting, combating misinformation, and the evolving future of financial media.
CoinRadar Daily content is written by named analysts and checked against our editorial standards. Market data is indicative and informational only — nothing here is financial advice.
Markets services, rated
How we score →Independent, rubric-scored tables covering the services this markets coverage keeps running into.
Best Crypto Exchanges
Top rated: Kraken 8.4
Centralised venues that hold your funds while you trade.
6rated →
Best Perpetual DEXs
Top rated: GMX 7.2
On-chain leverage.
4rated →
Best Crypto Trading Tools
Top rated: TradingView 8.5
Terminals, bots, screeners and portfolio trackers.
4rated →
Keep Reading
Risk Management for Crypto Investors: Sizing and Stops
Returns get the attention, but risk management decides who survives. Here is how position sizing, stop-losses, and sensible limits keep you in the game.
James Park · May 19, 2026→
Bull vs Bear Market: The Signals Worth Watching
Telling a bull market from a bear is easy in hindsight and hard in the moment. These are the signals that help you read the broader trend without chasing noise.
Emily Volker · May 26, 2026→
Crypto Market Cap Explained, and Why It Matters
Market cap is the headline number everyone quotes, but few use it correctly. Here is how it is calculated, what it really tells you, and where it can be misleading.
Olivia Bennett · June 1, 2026→