Skip to content

SYSTEM ONLINE

LIVE TAPE
BTC$75,897.00▲ 0.1%·
ETH$2,244.30▲ 0.3%·
USDT$0.999254▲ 0.0%·
BNB$694.63▼ 0.3%·
XRP$1.17▼ 1.7%·
USDC$0.999719▲ 0.0%·
SOL$89.99▼ 1.2%·
TRX$0.319695▲ 0.3%·
FIGR_HELOC$1.02▼ 1.3%·
ZEC$1,278.36▼ 7.0%·
HYPE$77.93▼ 1.5%·
XMR$613.32▼ 1.3%·
DOGE$0.071949▼ 1.5%·
USDS$1.00▲ 0.0%·
WBT$72.97▲ 0.2%·
LEO$9.33▲ 0.0%·
LINK$10.92▼ 0.6%·
ADA$0.182738▼ 3.3%·
BTC$75,897.00▲ 0.1%·
ETH$2,244.30▲ 0.3%·
USDT$0.999254▲ 0.0%·
BNB$694.63▼ 0.3%·
XRP$1.17▼ 1.7%·
USDC$0.999719▲ 0.0%·
SOL$89.99▼ 1.2%·
TRX$0.319695▲ 0.3%·
FIGR_HELOC$1.02▼ 1.3%·
ZEC$1,278.36▼ 7.0%·
HYPE$77.93▼ 1.5%·
XMR$613.32▼ 1.3%·
DOGE$0.071949▼ 1.5%·
USDS$1.00▲ 0.0%·
WBT$72.97▲ 0.2%·
LEO$9.33▲ 0.0%·
LINK$10.92▼ 0.6%·
ADA$0.182738▼ 3.3%·
Stablecoin Reserves: Cash, Bills and Repo Under Stress
LEAD STORYDeFi

Stablecoin Reserves: Cash, Bills and Repo Under Stress

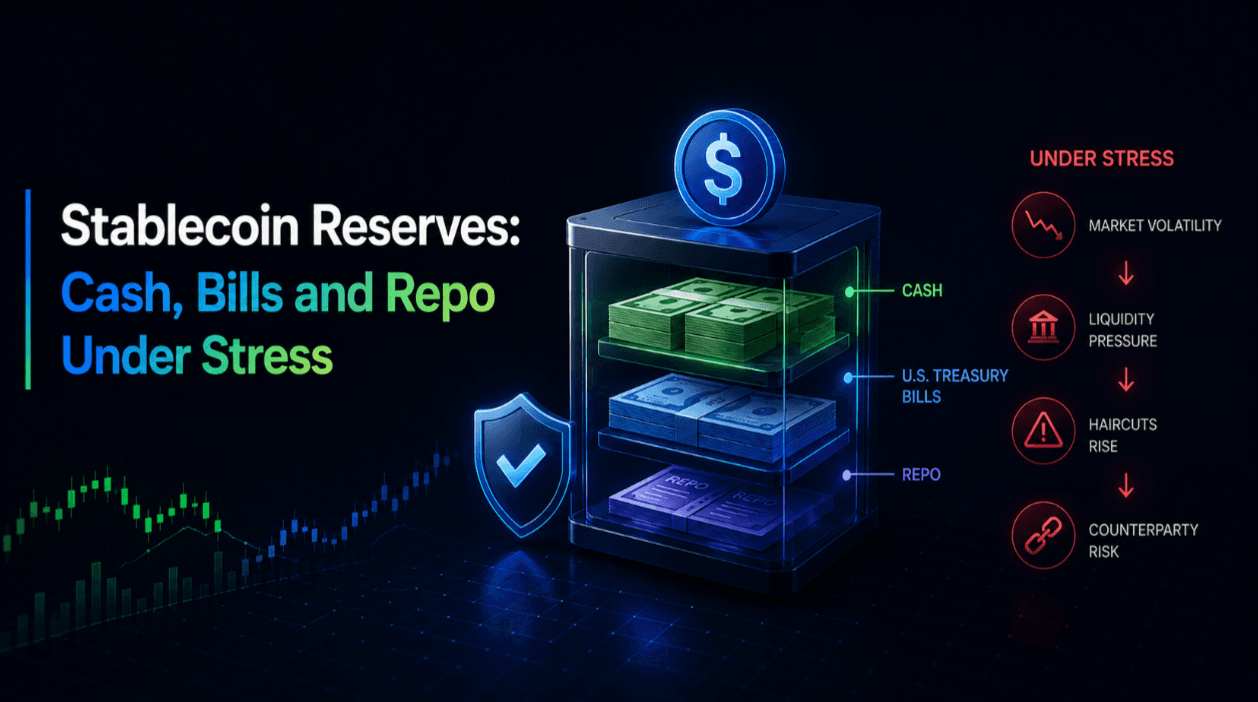
Two stablecoins can both be fully reserved and behave completely differently when holders want out at once. The reason is that reserves are a portfolio, and the three risks inside it — duration, credit and access — fail on different timescales.

◆ Emily Volker· Editor-in-Chief· 9 MIN· NOVEMBER 6, 2026
Markets

Market Maker Economics: Why Liquidity Leaves When You Need It

The most reliable observation in market structure is that liquidity is abundant when you do not need it and absent when you do. That is not a failure of the participants providing it — it is the direct consequence of how they get paid and how they lose.

Olivia Bennett · November 4, 2026→

Markets

Sequencers: The Trust Assumption Inside On-Chain Trading

Trading on a rollup is described as on-chain, and settlement genuinely is. Ordering usually is not. A single operator decides what goes into each block and in what order, and the protections against that are real but narrower than the phrase suggests.

James Park · November 2, 2026→

Markets

Exchange Insurance Funds: How They Are Built and When They Fail

Derivatives venues advertise an insurance fund as though it were deposit protection. It is a buffer against one specific accounting problem, it is funded by the traders it protects, and the number that matters is not its size but its size relative to what could hit it.

Emily Volker · October 31, 2026→

DESK // 002

Analysis & Long Reads

VIEW ALL →
Proof of Reserves: What It Shows and What It Cannot
Markets· 8 min

Proof of Reserves: What It Shows and What It Cannot

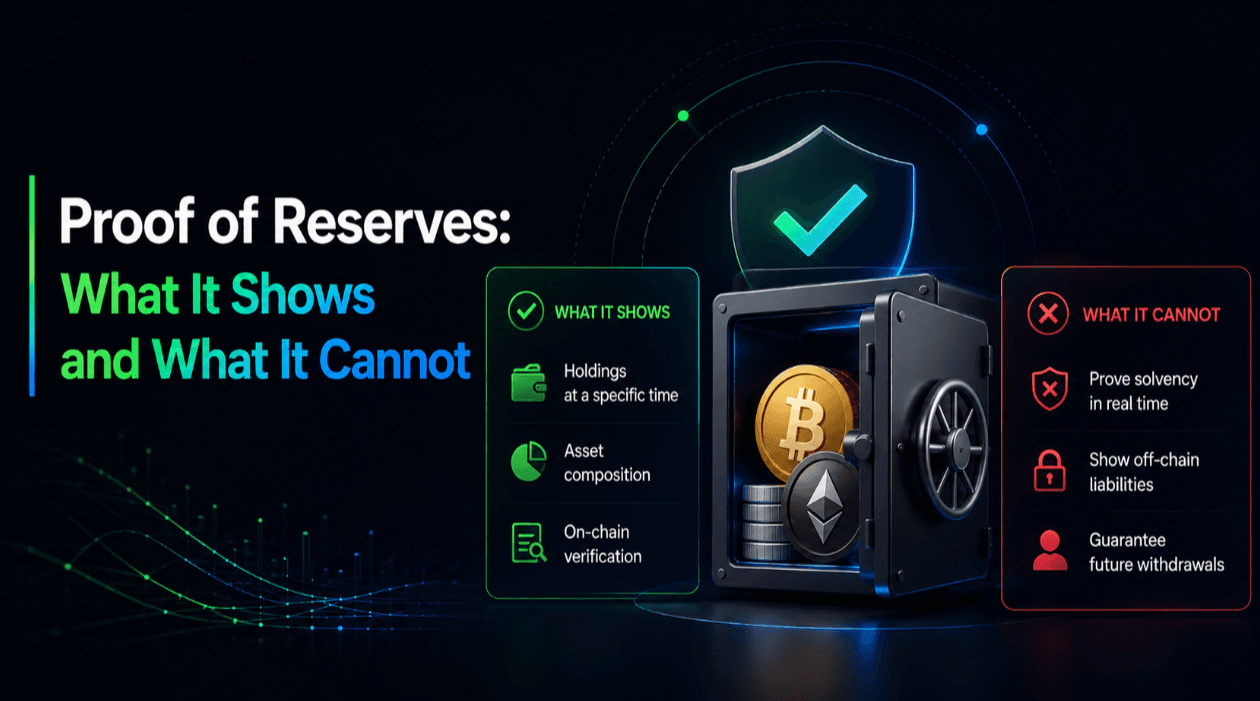
Proof of reserves is the standard answer to whether an exchange has your money, and it answers a narrower question than the name implies. Knowing exactly which question it answers is the difference between a useful check and false comfort.

Olivia Bennett · October 29, 2026→

Oracle Latency: How a Price Feed Decides Who Gets Liquidated
Markets· 9 min

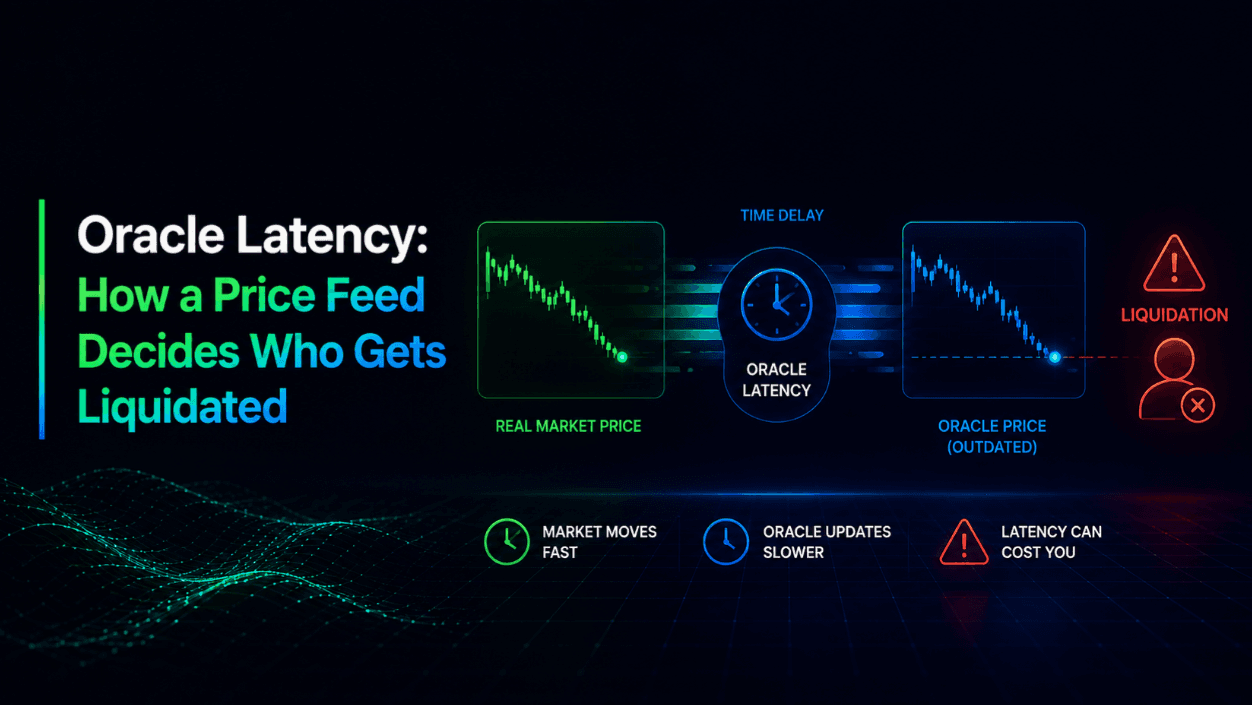
Oracle Latency: How a Price Feed Decides Who Gets Liquidated

A lending protocol cannot see the market. It sees whatever its oracle last told it, and every liquidation, every borrow limit and every solvency check runs on that figure. The gap between the reported price and the real one is where a specific and expensive class of failure lives.

James Park · October 27, 2026→

Liquidation Engines: Partial, Full and Auction Designs
Markets· 9 min

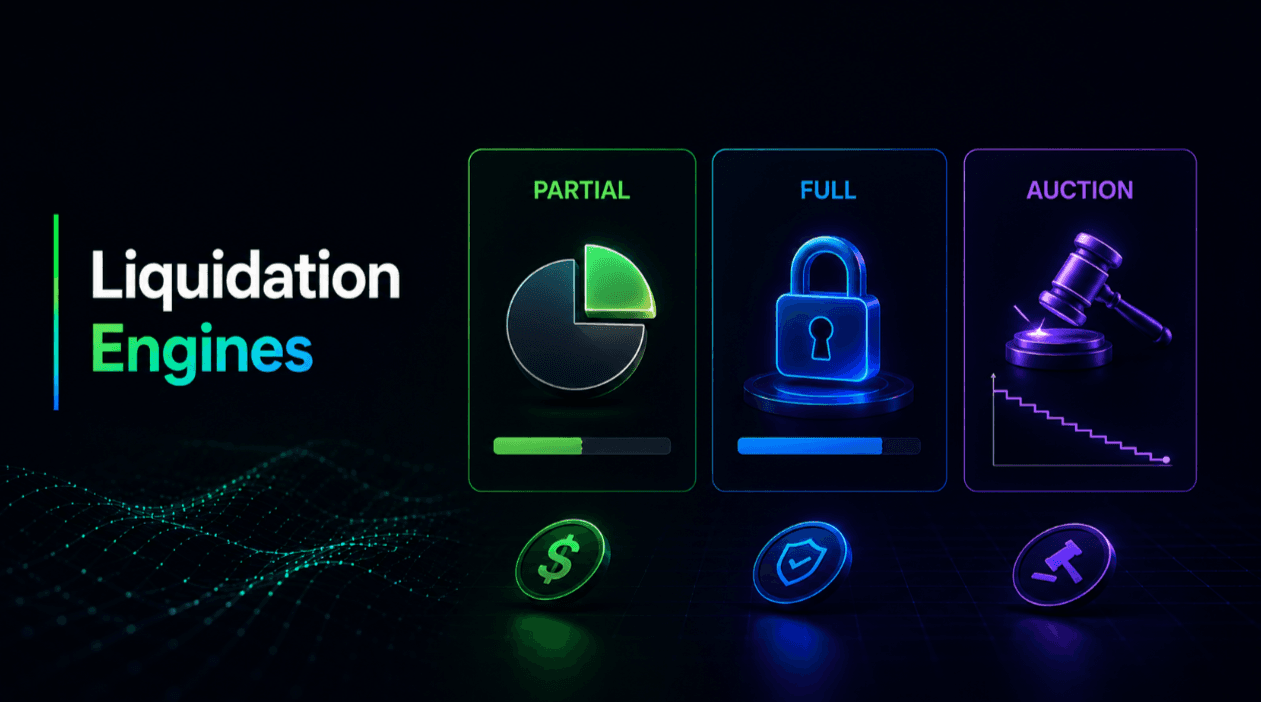
Liquidation Engines: Partial, Full and Auction Designs

Every leveraged venue has a mechanism for closing positions that can no longer support themselves. The design of that mechanism decides whether a sharp move costs you your position, part of it, or more than you deposited.

Emily Volker · October 25, 2026→

Funding Rates: What They Price and When They Mislead
Markets· 8 min

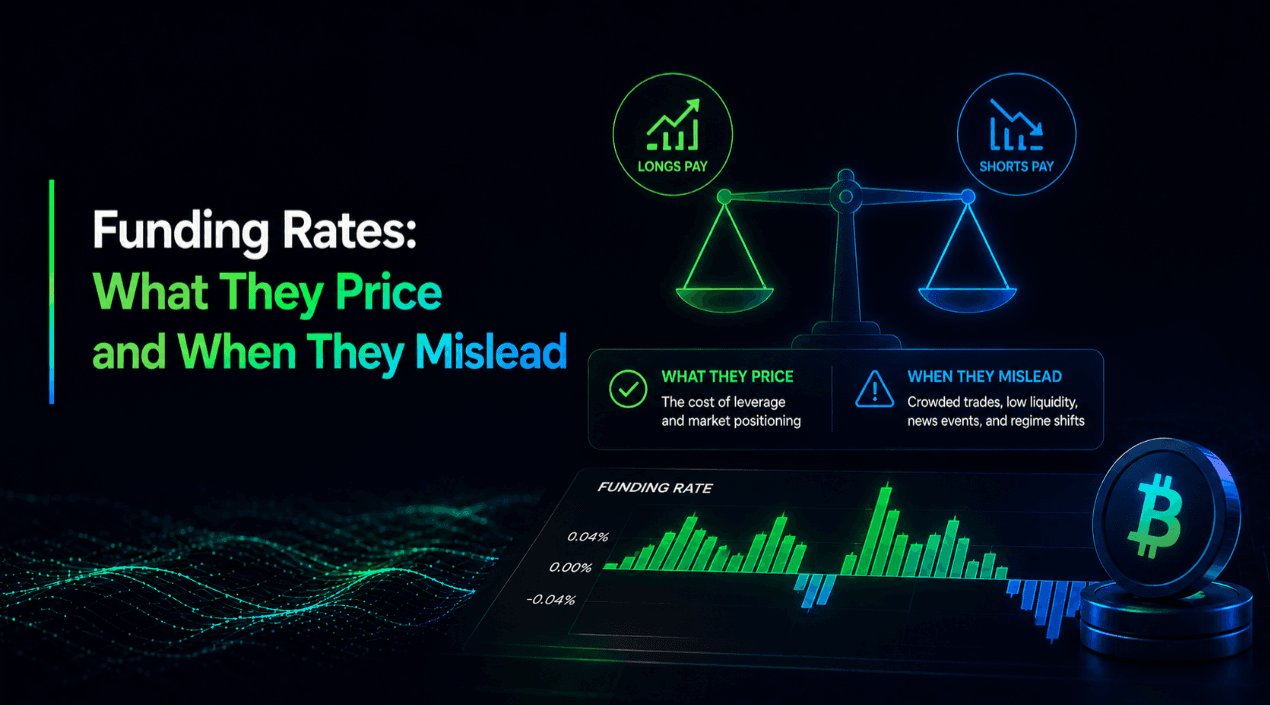
Funding Rates: What They Price and When They Mislead

Funding is the mechanism that stops a contract with no expiry from drifting away from the asset it tracks. It is routinely read as a measure of market sentiment, which is a plausible interpretation and an unreliable one.

Olivia Bennett · October 23, 2026→

MEV for Traders: What It Costs You and What Helps
Markets· 9 min

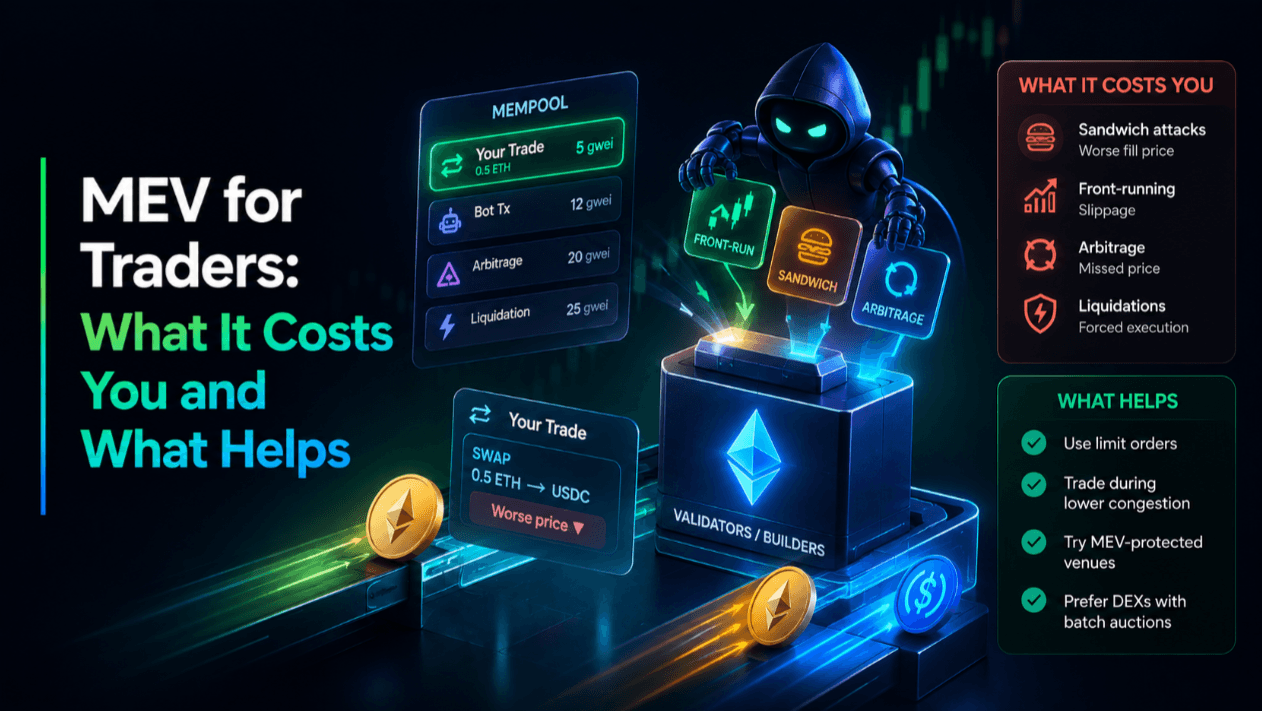
MEV for Traders: What It Costs You and What Helps

On a public chain, a transaction is visible to everyone before it is final. That visibility has a price, most traders pay it without noticing, and the amount they pay is partly set by a wallet setting they were told to increase when transactions failed.

James Park · October 21, 2026→

Maker-Taker Fees and the Book They Produce
Markets· 8 min

Maker-Taker Fees and the Book They Produce

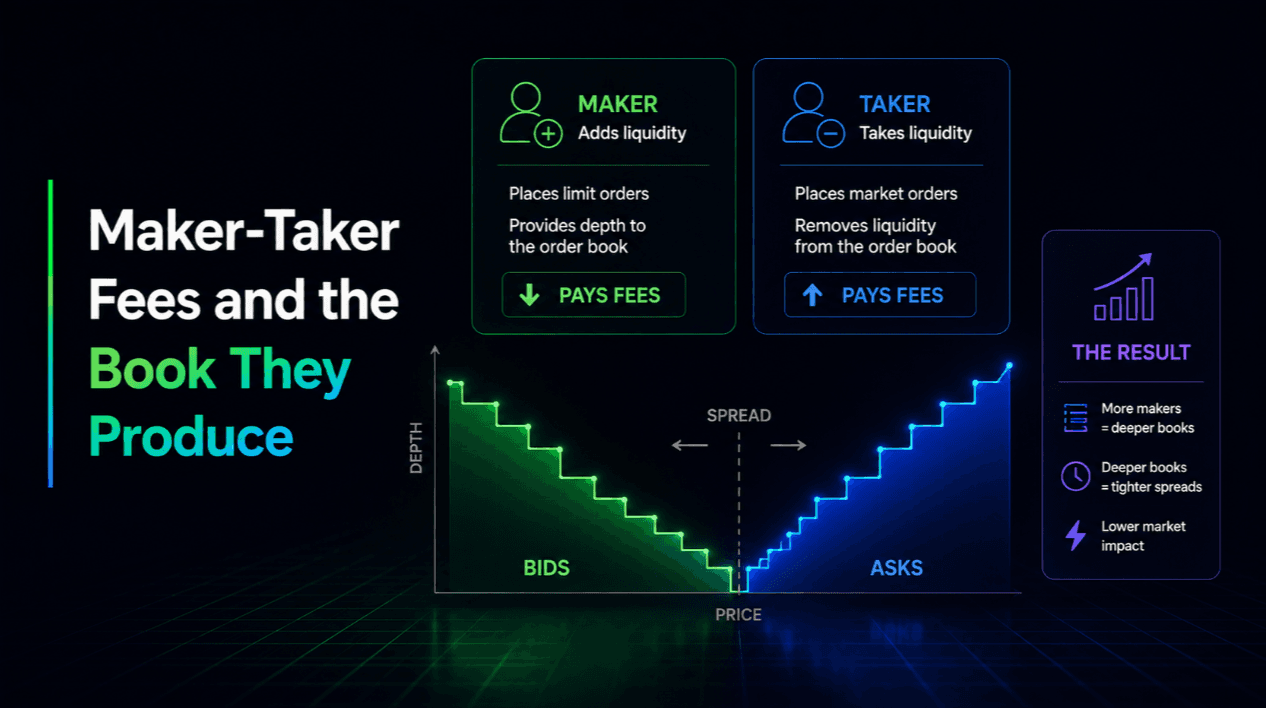
Almost every venue charges more to take liquidity than to provide it, and some pay providers outright. The stated reason is fairness to market makers. The actual effect is that the depth on your screen is partly a product of the fee schedule rather than of genuine willingness to trade.

Emily Volker · October 19, 2026→

RATINGS // 003

Ratings & Rankings

ALL RATINGS →