Maker-Taker Fees and the Book They Produce
Almost every venue charges more to take liquidity than to provide it, and some pay providers outright. The stated reason is fairness to market makers. The actual effect is that the depth on your screen is partly a product of the fee schedule rather than of genuine willingness to trade.
By Emily Volker, Editor-in-Chief
Editorial Strategy, Investigative Journalism, Crypto Media, E-E-A-T Standards
✓ Reviewed by James Park· NFT & Web3 Gaming Analyst
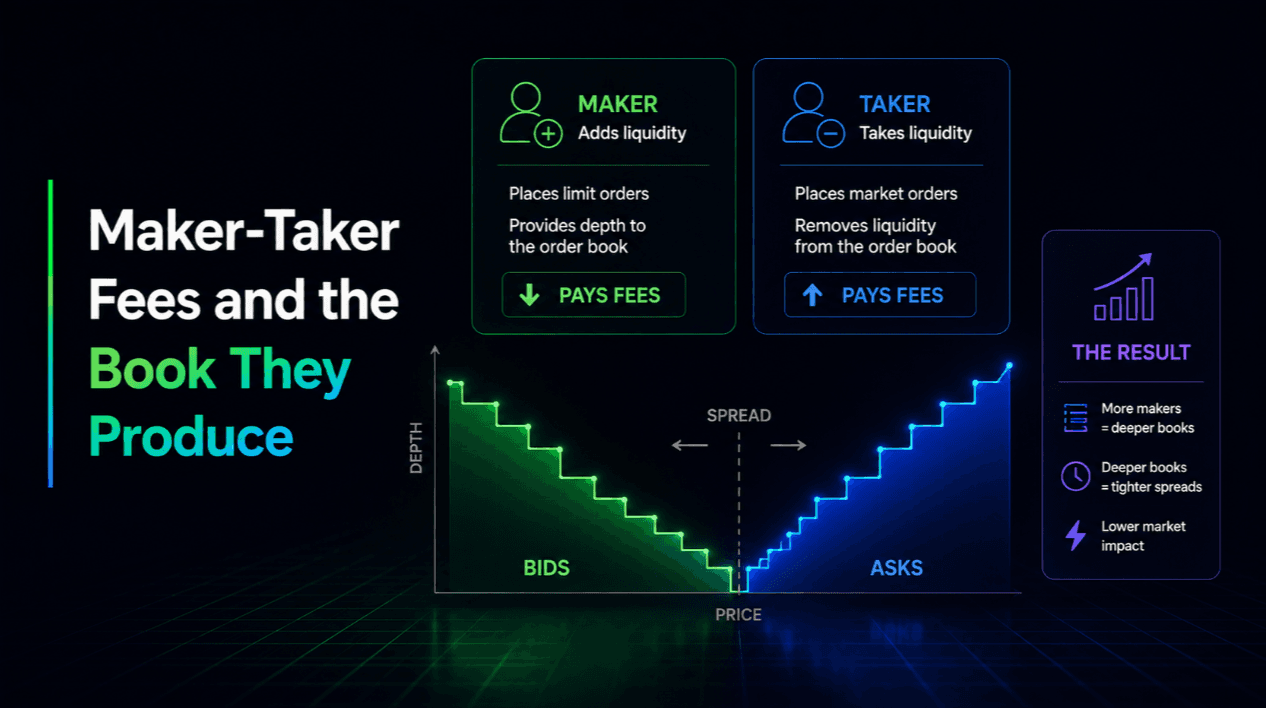
A maker order adds to the book and waits. A taker order removes from it immediately. Venues charge these differently — takers more, makers less or negative — and the gap between the two rates does more to shape a market than any other parameter a venue controls.
Why venues pay for liquidity
A venue with no resting orders is not a market. The first problem any exchange has is attracting participants willing to quote before there is volume to justify quoting, and a fee rebate is the direct solution: pay people to post, and the book fills.
Once liquidity exists, it attracts volume, which produces taker fees, which fund the rebates. The model is self-sustaining as long as taker flow exceeds what the rebates cost, and the spread between the two rates is the venue's margin.
That is a coherent design. It is also why comparing venues on their headline taker fee alone is misleading — a venue with a high taker fee and a large rebate may have far better depth than one with a low taker fee and none.
What the rebate manufactures
The complication is that a rebate rewards posting rather than being willing to trade, and those are not the same thing.
An order posted primarily to earn a rebate is intended to be cancelled if the market moves toward it. It counts as displayed depth, it makes the book look thick, and it withdraws precisely when someone wants to use it. This is not deception; it is the rational response to being paid for presence rather than for execution.
The practical consequence is that displayed depth on a heavily rebated venue overstates what you can actually trade against, and the overstatement is largest during volatility. A trader sizing an order from the book is reading a number partly generated by an incentive.
This is measurable. Fill rate against displayed size, and how far the price moves relative to what the book predicted, both reveal the gap. Venues do not publish it; anyone trading at size can compute it for themselves.
The tier structure and who it favours
Fee schedules are tiered by volume, and the tiers span a wide range. The top tier frequently pays makers a rebate and charges takers very little, while the bottom tier pays nothing and charges several times more.
The effect is that the same trade costs materially different amounts depending on who executes it, and the difference is larger than most retail traders assume. A strategy that is marginally profitable at top-tier rates can be firmly unprofitable at bottom-tier ones, which is a large part of why published backtests rarely survive contact with a retail account.
It also means fee comparisons between venues are only meaningful at a stated volume. A venue that is cheapest at high volume can be the most expensive at low volume, and both facts appear on the same page.
Where the model does not apply
Automated market makers have no maker-taker distinction because there are no resting orders — liquidity providers earn a share of fees paid by every trade regardless of direction, and there is nothing to cancel.
That removes the phantom-depth problem entirely: pool liquidity is capital actually committed, and it cannot be withdrawn in the moment before your trade lands. It introduces the opposite issue, which is that the capital cannot be repositioned quickly when it should be.
The comparison is therefore not which venue has better fees but which failure you prefer: depth that can vanish, or depth that cannot get out of the way.
Reading a fee schedule properly
- Find your actual tier, not the headline rate. The gap between top and bottom tiers is larger than the gap between most venues.
- Note whether the maker rate is a reduced fee or a genuine rebate, since the second manufactures more phantom depth than the first.
- Measure fill rate against displayed size rather than trusting the book, particularly during volatile periods.
- Include withdrawal and funding costs. A venue with excellent trading fees and expensive withdrawals is not cheap.
- Compare total cost at your volume, and re-check it if your volume changes — the ranking moves.
Sources
2 references- 01The Uniswap Protocol
Uniswap · accessed August 22, 2026
- 02Concentrated liquidity
Uniswap · accessed August 22, 2026
Frequently asked questions
Why do exchanges pay maker rebates?+
To attract resting orders before there is enough volume to make quoting worthwhile. Liquidity attracts volume, volume produces taker fees, and those fund the rebates. The spread between the taker and maker rates is the venue's margin, which is why headline taker fees alone tell you little.
Does a thick order book mean a liquid market?+
Not necessarily. Rebates reward posting rather than trading, so orders placed to earn them are designed to be cancelled if the market approaches. Displayed depth on a heavily rebated venue overstates what you can trade against, and most so during volatility.
How much do fee tiers actually matter?+
More than most traders assume. The range between top and bottom tiers usually exceeds the difference between venues, and a strategy profitable at top-tier rates can be firmly unprofitable at retail ones. Fee comparisons are only meaningful at a stated volume.
Do AMMs have maker-taker fees?+
No — there are no resting orders to make or take. Liquidity providers earn a share of fees on every trade. That removes phantom depth entirely, since pool capital cannot be pulled in the moment before your trade lands, and replaces it with capital that cannot reposition quickly.
Written by
Emily VolkerEditor-in-ChiefEditorial Strategy, Investigative Journalism, Crypto Media, E-E-A-T Standards
Emily Volker is the Editor-in-Chief of CoinRadar Daily, where she leads a multilingual editorial team covering cryptocurrency markets, blockchain innovation, Web3, and global digital asset regulation across eight languages. With more than a decade of experience in financial and technology journalism, she has played a key role in developing high editorial standards and trusted reporting within the digital asset industry. Emily began her career as a financial journalist reporting on commodities, energy markets, and emerging technologies before discovering Bitcoin and decentralized finance in the early 2010s. She later moved to London to join one of Europe's early blockchain-focused media organizations, where she advanced into senior editorial leadership. Her experience reporting through both the rapid expansion of the 2017 ICO boom and the subsequent market correction reinforced her commitment to fact-based, research-driven journalism in an industry often influenced by speculation. She holds a Master's degree in International Journalism from City, University of London, and has completed executive studies in digital media strategy through the Reuters Institute at Oxford. Emily is a strong advocate for editorial transparency, rigorous verification, and responsible financial reporting. She also helped integrate Google's E-E-A-T principles—Experience, Expertise, Authoritativeness, and Trustworthiness—into the editorial standards followed by CoinRadar Daily. Under her leadership, CoinRadar Daily has expanded into a global cryptocurrency news platform publishing content in eight languages with a network of editors, analysts, and contributors across four continents. Emily oversees investigative reporting, editorial policy, content quality, and fact-checking processes to ensure every article meets the publication's standards for accuracy, credibility, and independence. Alongside her editorial responsibilities, Emily mentors aspiring journalists through digital media initiatives and regularly speaks at international conferences focused on journalism, fintech, blockchain technology, and digital assets, where she discusses responsible reporting, combating misinformation, and the evolving future of financial media.
✓Reviewed & edited by
James ParkNFT & Web3 Gaming AnalystNFTs, Web3 Gaming, GameFi, Digital Collectibles, Creator Economy
James Park serves as the NFT & Web3 Gaming Analyst at CoinRadar Daily, where he covers the rapidly evolving worlds of blockchain gaming, digital collectibles, metaverse ecosystems, and creator-driven economies. Combining expertise in interactive media with blockchain technology, he analyzes how NFTs and decentralized gaming continue to reshape digital ownership and online communities. James earned a Master of Fine Arts in Digital Media from NYU Tisch School of the Arts, giving him a unique perspective that blends creative storytelling, digital culture, and emerging technology. Rather than viewing NFTs solely through an investment lens, he examines their broader impact on entertainment, gaming, intellectual property, and community engagement. Prior to joining CoinRadar Daily, James reported on the NFT industry and blockchain gaming for several leading digital media outlets, covering the explosive growth of the NFT market, the transition toward utility-focused collections, and the evolution of GameFi. His close relationships with independent developers, digital artists, and gaming communities allow him to identify important industry trends long before they reach mainstream attention. His reporting places particular emphasis on sustainable Web3 game design, token economies, and the long-term viability of blockchain-powered virtual worlds. James has published extensive research analyzing why certain gaming ecosystems thrive while others struggle with inflationary token models, weak player retention, or unsustainable reward structures. His market analysis is frequently referenced by blockchain startups, investors, and game studios evaluating new Web3 projects. Beyond journalism, James actively participates in NFT and decentralized creator communities while following developments in digital art, virtual economies, and next-generation gaming technologies. He also contributes educational content on blockchain gaming and regularly speaks about the future of digital ownership, helping CoinRadar Daily deliver balanced, research-driven coverage at the intersection of technology, gaming, and crypto innovation.
CoinRadar Daily content is written by named analysts and checked against our editorial standards. Market data is indicative and informational only — nothing here is financial advice.
Markets services, rated
How we score →Independent, rubric-scored tables covering the services this markets coverage keeps running into.
Best Crypto Exchanges
Top rated: Kraken 8.4
Centralised venues that hold your funds while you trade.
6rated →
Best Perpetual DEXs
Top rated: GMX 7.2
On-chain leverage.
4rated →
Best Crypto Trading Tools
Top rated: TradingView 8.5
Terminals, bots, screeners and portfolio trackers.
4rated →
Keep Reading
Risk Management for Crypto Investors: Sizing and Stops
Returns get the attention, but risk management decides who survives. Here is how position sizing, stop-losses, and sensible limits keep you in the game.
James Park · May 19, 2026→
Bull vs Bear Market: The Signals Worth Watching
Telling a bull market from a bear is easy in hindsight and hard in the moment. These are the signals that help you read the broader trend without chasing noise.
Emily Volker · May 26, 2026→
Crypto Market Cap Explained, and Why It Matters
Market cap is the headline number everyone quotes, but few use it correctly. Here is how it is calculated, what it really tells you, and where it can be misleading.
Olivia Bennett · June 1, 2026→