Order Books and AMM Curves: Where Each One Prices Better
An order book and an automated market maker solve the same problem — matching a buyer to a seller — with opposite assumptions about who is willing to wait. Neither is better in general, and knowing which is better for a given trade is a question with an actual answer.
By James Park, NFT & Web3 Gaming Analyst
NFTs, Web3 Gaming, GameFi, Digital Collectibles, Creator Economy
✓ Reviewed by Olivia Bennett· Blockchain Security Researcher
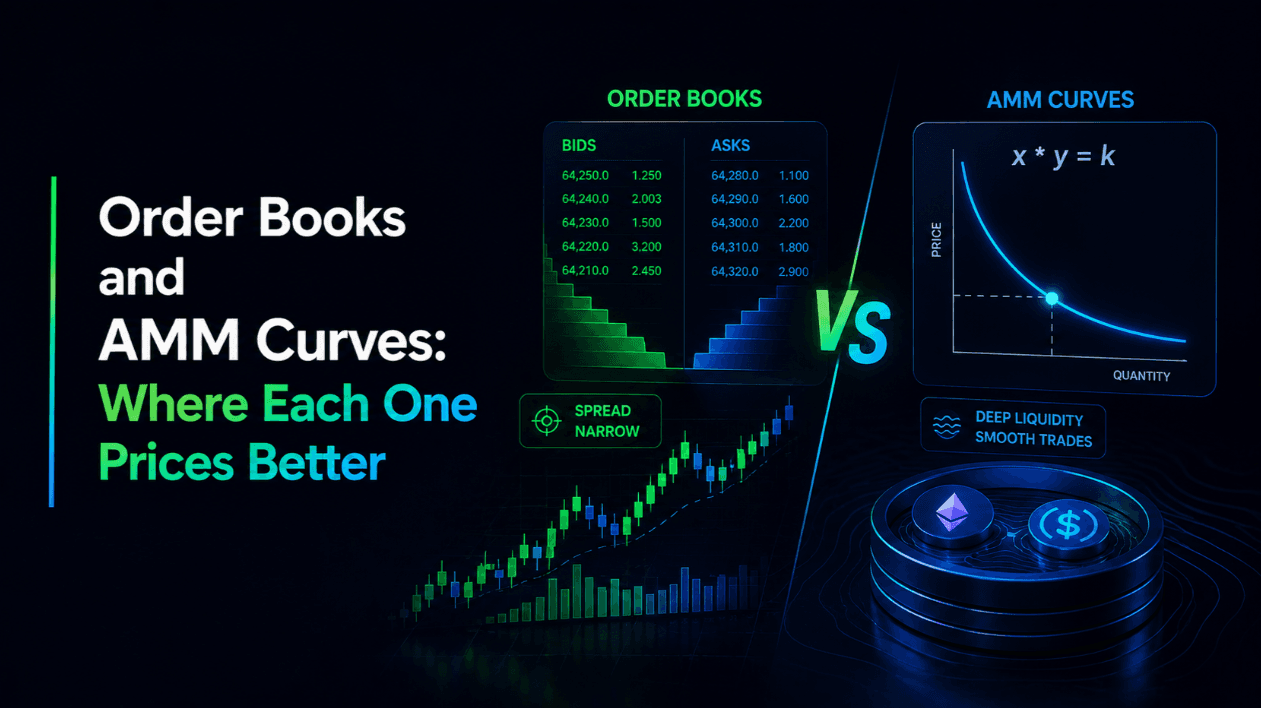
In an order book, participants post the prices at which they will buy or sell, and a trade happens when two orders meet. In an automated market maker, a formula sets the price from the ratio of assets in a pool, and anyone can trade against it at whatever that formula says. The first requires someone on the other side to be waiting; the second guarantees a counterparty and lets the price move to compensate.
What the book gives you
Precision. A limit order executes at your price or not at all, which is a control an AMM cannot offer natively — you are choosing certainty of price over certainty of execution.
Depth that can be inspected. You can see the size available at each level and calculate what a given trade would cost before placing it. Whether that displayed depth survives contact with a real order is another matter, but the information exists.
And efficiency at scale. A liquid book concentrates offers near the current price without requiring anyone to lock capital across a range they think is irrelevant, which is why professional market making has always preferred them.
The cost is that the book only works when someone is making it. In a thin market the spread widens until the quoted price is close to fiction, and in a fast one the displayed depth vanishes as makers pull quotes — precisely when you wanted it.
What the curve gives you
A counterparty, always. There is no state in which an AMM refuses to trade; the price simply moves further as the trade grows. For long-tail assets nobody is willing to quote continuously, that guarantee is the difference between a market and no market.
Passive participation. Providing liquidity requires depositing assets and nothing else — no quoting, no infrastructure, no monitoring. That opened market making to people who could never have run a book, which is why AMMs bootstrapped liquidity for thousands of assets that would otherwise have had none.
Transparency of the pricing rule. The formula is public and the reserves are on-chain, so anyone can compute the exact price for any trade size in advance. No book offers that, because a book's future depth depends on the intentions of participants.
The cost is that the curve prices without knowing anything. It has no view on value; it responds only to the trades it receives, which means it is systematically on the wrong side when prices move on external information. Liquidity providers absorb that as a loss relative to simply holding the assets, and it is the fundamental economics of the design rather than a flaw in it.
The size question
Trade size is what usually decides between them.
Small trades in an active market are frequently cheaper on a curve. There is no waiting, price impact is negligible relative to the spread you would cross in a book, and the execution is deterministic.
Large trades are usually cheaper in a deep book, because depth can be concentrated exactly where the trading is happening rather than spread across a range. A curve holds liquidity at prices nobody is trading at, which is capital doing nothing while still counting toward the pool.
Concentrated liquidity narrows this gap considerably by letting providers deploy within a chosen band, which makes a curve behave much more like a book near the active price — and reintroduces the active management that passive provision was meant to avoid.
How they fail
A book fails by emptying. Makers withdraw, the spread widens, and a market that looked liquid a moment ago cannot absorb an ordinary order. The failure is discontinuous and it happens exactly when volatility spikes.
A curve fails by pricing. It never refuses, so a large trade against a thin pool executes at a terrible price rather than not executing. The failure is continuous and visible in advance, which is a meaningful difference: you can compute the bad outcome before accepting it.
Which failure is preferable depends on whether you would rather be unable to trade or able to trade badly. For a liquidation engine that must execute, the curve's guarantee is worth a great deal. For a discretionary trade, the book's refusal is information.
Choosing for a given trade
- Compute the curve's price for your exact size before comparing — it is deterministic and takes seconds.
- For a book, treat displayed depth as an upper bound rather than a promise, especially in volatile conditions.
- Small trades in liquid pairs: the curve is usually cheaper once the spread is counted.
- Large trades: compare against concentrated-liquidity pools specifically, not against a general-purpose curve.
- For long-tail assets there is frequently no choice, and the relevant question becomes how thin the pool is rather than which venue.
The useful framing is that a book prices by asking people and a curve prices by rule. Rules are predictable and uninformed; people are informed and unreliable. Every trade-off between the two designs descends from that.
Sources
2 references- 01The Uniswap Protocol
Uniswap · accessed August 22, 2026
- 02Concentrated liquidity
Uniswap · accessed August 22, 2026
Frequently asked questions
Is an AMM cheaper than an order book?+
For small trades in an active market, often yes — no waiting, minimal price impact, and no spread to cross. For large trades a deep book is usually cheaper, because depth can be concentrated where trading actually happens rather than spread across prices nobody is using.
Why do AMM liquidity providers lose money relative to holding?+
Because the curve prices without any view on value. When the market moves on outside information, the pool is systematically on the wrong side until arbitrage corrects it, and that transfer is a structural feature of the design rather than a bug. Fee income is what compensates for it.
What is concentrated liquidity?+
Deploying pool capital within a chosen price band rather than across the whole range. It makes a curve behave much more like a book near the active price and greatly improves capital efficiency — at the cost of reintroducing the active management that passive provision was designed to avoid.
Which one fails more safely?+
They fail differently. A book empties when makers pull quotes, so you cannot trade at all — a discontinuous failure that arrives with volatility. A curve never refuses, so a large trade against a thin pool simply executes at a bad price, which is at least computable in advance.
Written by
James ParkNFT & Web3 Gaming AnalystNFTs, Web3 Gaming, GameFi, Digital Collectibles, Creator Economy
James Park serves as the NFT & Web3 Gaming Analyst at CoinRadar Daily, where he covers the rapidly evolving worlds of blockchain gaming, digital collectibles, metaverse ecosystems, and creator-driven economies. Combining expertise in interactive media with blockchain technology, he analyzes how NFTs and decentralized gaming continue to reshape digital ownership and online communities. James earned a Master of Fine Arts in Digital Media from NYU Tisch School of the Arts, giving him a unique perspective that blends creative storytelling, digital culture, and emerging technology. Rather than viewing NFTs solely through an investment lens, he examines their broader impact on entertainment, gaming, intellectual property, and community engagement. Prior to joining CoinRadar Daily, James reported on the NFT industry and blockchain gaming for several leading digital media outlets, covering the explosive growth of the NFT market, the transition toward utility-focused collections, and the evolution of GameFi. His close relationships with independent developers, digital artists, and gaming communities allow him to identify important industry trends long before they reach mainstream attention. His reporting places particular emphasis on sustainable Web3 game design, token economies, and the long-term viability of blockchain-powered virtual worlds. James has published extensive research analyzing why certain gaming ecosystems thrive while others struggle with inflationary token models, weak player retention, or unsustainable reward structures. His market analysis is frequently referenced by blockchain startups, investors, and game studios evaluating new Web3 projects. Beyond journalism, James actively participates in NFT and decentralized creator communities while following developments in digital art, virtual economies, and next-generation gaming technologies. He also contributes educational content on blockchain gaming and regularly speaks about the future of digital ownership, helping CoinRadar Daily deliver balanced, research-driven coverage at the intersection of technology, gaming, and crypto innovation.
✓Reviewed & edited by
Olivia BennettBlockchain Security ResearcherSmart Contract Security, Audit Reports, Exploits, DeFi Hacks, White-Hat Research
Olivia Bennett is the Blockchain Security Researcher at CoinRadar Daily, where she specializes in smart contract security, DeFi risk analysis, blockchain infrastructure, and protocol vulnerabilities. Drawing on years of hands-on cybersecurity experience, she delivers in-depth reporting that explains both the technical details and the real-world implications of security incidents across the digital asset ecosystem. Before joining CoinRadar Daily, Olivia built her career in cybersecurity, working in penetration testing, blockchain security assessments, and smart contract auditing. She participated in numerous security reviews for decentralized applications and blockchain protocols, helping identify critical vulnerabilities before they could be exploited. Her responsible disclosure work has contributed to improving the security of several major DeFi projects and protecting millions of dollars in digital assets. Olivia earned a Bachelor of Science in Computer Science from the University of Edinburgh and later completed advanced professional training in offensive security and blockchain technologies. Her combination of software security expertise and blockchain knowledge enables her to provide readers with clear, evidence-based analysis of exploits, protocol upgrades, and emerging attack vectors. At CoinRadar Daily, Olivia publishes detailed investigations into blockchain exploits, smart contract audits, cross-chain security, wallet protection, and evolving cyber threats affecting the crypto industry. She is particularly committed to translating highly technical research into practical guidance that helps investors, developers, and blockchain users better understand protocol risk and security best practices. Alongside her editorial work, Olivia contributes educational resources covering secure wallet management, decentralized finance security, and blockchain infrastructure. She also participates in industry events and technical discussions focused on strengthening Web3 security standards, supporting CoinRadar Daily's mission to provide accurate, research-driven coverage of the rapidly evolving digital asset landscape.
CoinRadar Daily content is written by named analysts and checked against our editorial standards. Market data is indicative and informational only — nothing here is financial advice.
Markets services, rated
How we score →Independent, rubric-scored tables covering the services this markets coverage keeps running into.
Best Crypto Exchanges
Top rated: Kraken 8.4
Centralised venues that hold your funds while you trade.
6rated →
Best Perpetual DEXs
Top rated: GMX 7.2
On-chain leverage.
4rated →
Best Crypto Trading Tools
Top rated: TradingView 8.5
Terminals, bots, screeners and portfolio trackers.
4rated →
Keep Reading
Risk Management for Crypto Investors: Sizing and Stops
Returns get the attention, but risk management decides who survives. Here is how position sizing, stop-losses, and sensible limits keep you in the game.
James Park · May 19, 2026→
Bull vs Bear Market: The Signals Worth Watching
Telling a bull market from a bear is easy in hindsight and hard in the moment. These are the signals that help you read the broader trend without chasing noise.
Emily Volker · May 26, 2026→
Crypto Market Cap Explained, and Why It Matters
Market cap is the headline number everyone quotes, but few use it correctly. Here is how it is calculated, what it really tells you, and where it can be misleading.
Olivia Bennett · June 1, 2026→